
Northern Ireland weekly market report 11 November 2025
Northern Ireland weekly market report: 11 November 2025
11 November 2025
Grains
UK feed wheat futures (May-26)

UK feed wheat futures (May-26) traded above the 20-day simple moving average last week (31 October – 07 November), remaining above the support level of £173/t.
The relative strength index (RSI) rose to 62, up from 56 in the previous week, suggesting an increase in market momentum.
Market drivers
Global wheat futures rose to a two-month high in the middle of last week but eased towards the end of the week. The initial gains were driven by hopes of renewed Chinese interest in US-origin wheat, but this soon subsided as expectations fell short. Towards the end of the week, US maize harvest pressure ensued and benign weather in both the US and Europe meant ample global supplies came back into focus.
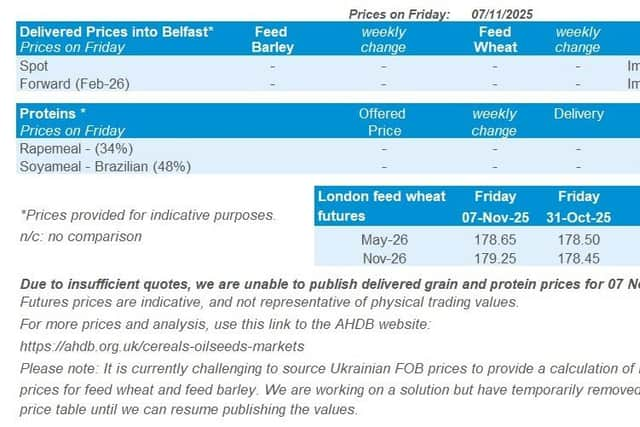
Despite the gains in the middle of the week, UK feed wheat broadly tracked sideways week on week, shadowing the movements in Paris milling wheat futures. The May-26 contract closed at £178.65/t, up £0.15/t (0.1%) on the week, while Paris milling wheat (May-26) ended down 0.3%, pressured by weaker US market sentiment.
The main support last week was reports that Chinese importers had reportedly booked 120 Kt of US wheat for December shipment. Further to that, it was reported that a US sorghum shipment was heading to China (LSEG). This came following a meeting between President Trump and Xi to discuss easing trade tensions. Markets soon subdued back down after digesting this news and awaited fresh commitments.
Across the US, the maize harvest is now 83% complete, helped by dry weather in the Midwest. 2026 winter wheat drilling is almost finished, with 91% of the crop sown and 52% rated good to excellent, this is according to a Reuters poll, not official USDA data.
In Brazil, planting of the country’s first 2025/26 maize crop is 72% complete in the key centre-south region, broadly in line with 72.5% at the same point last year (AgRural). Brazil’s 2025/26 maize production is estimated at 142.5Mt by Safra, substantially higher than the USDA’s projection of 131.0Mt. Meanwhile, in Argentina, the wheat harvest is around 12% complete. The Buenos Aires Grain Exchange has maintained its forecast for a 22.0Mt for 2025/26, up from 18.6Mt last year.
Sovecon has raised its forecast for Russian wheat exports in 2025/26 by 0.4 Mt to 43.8 Mt, reflecting better crop prospects. Furthermore, it was reported last week that the Russian government is considering introducing a 20 Mt grain export quota for the period 15 February to 30 June 2026, following a draft document published by the Russian Grain Union lobby group. Last season’s quota for the same period was 10.6 Mt and covered only wheat and meslin, but the proposed quota would also include maize and barley (LSEG).
For 2026 harvest the European winter grains campaign is progressing well. French soft wheat and winter barley planting (to 03 Nov) were 79% and 87% complete, respectively, both ahead of five-year averages.
Rapeseed
Paris rapeseed futures in £/t (May-26)
In £/t terms, May-26 Paris rapeseed futures decreased last week (31 October – 07 November), closing again above the 20-day moving average near £420/t. The 20-day moving average could be the nearest potential support price level.
The relative strength index (RSI) fell from 71 to 68, indicating a decrease in market momentum and signalling a move away from the overbought zone.
Market drivers
Chicago soyabean futures (May-26) were set for their first weekly drop in 4 weeks, but ended the week up 0.2% from bargain buying, as new around US and China’s trade deal is in the spotlight. Meanwhile Paris rapeseed futures (May-26) fell €1.00/t (0.2%) on the week (Friday-Friday) closing at €477.50/t on Friday, following marginal pressure in crude oil and benign news around EU rapeseed crop development.
The oilseed market is still focused on the relations between the US and China following a truce agreement made recently that China would purchase 12Mt of US-origin soyabeans over November and December, which currently have not materialised. Furthermore, the US government shutdown is adding to uncertainty over Chinese demand as the USDA flash export sales reporting system is not operating.
In Europe, there are anticipations that the EU rapeseed area for 2026/27 will rise, with Expana publishing last week that the sown area is estimated to rise by 7% with provisional estimates at 6.46Mha, with early-sown rapeseed seeing an increase due to better margins than cereals, for the most part sowing of winter crops in Europe has been benign and without a significant weather event.