
Northern Ireland weekly market report - 12 May 2025
Northern Ireland weekly market report - 12 May 2025
12 May 2025
Grains
UK feed wheat futures (Nov-25)
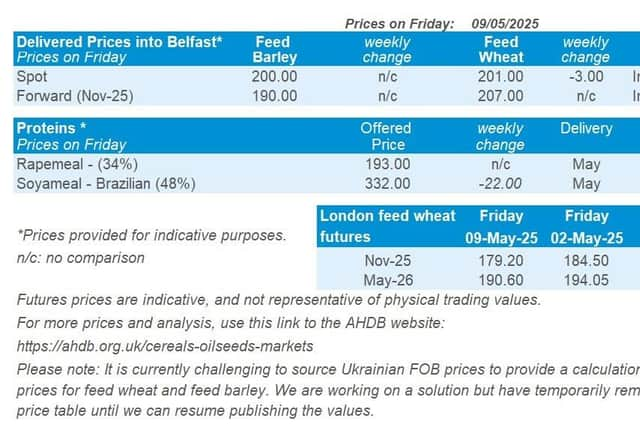

Nov-25 futures fell last week, closing near the support level of £175/t. Currently futures are well below the 20-day moving average. An RSI at 32 (near oversold), could indicate some technical support in the absence of pressure from fundamental factors.
Market drivers
Domestic feed wheat futures fell 2.9% Friday to Friday last week, following Chicago and Paris grain futures. Updates on the development of northern hemisphere crops, as well as global export demand remain key market drivers.
Last week the USDA reported improved winter wheat conditions in the US, with 51% rated in good or excellent condition as at 04 May, compared to 49% a week earlier. Additionally, favourable conditions mean 40% of the country’s maize crop had been planted, versus 24% a week earlier, and 35% a year before.
US wheat export sales for the week ending 01 May were reported at 69.7 Kt, down 3% on a week earlier. Net export sales of maize rose 64% week-on-week to 1.66 Mt. The spread between Chicago wheat and maize continues to narrow.
Chinese buyers bought between 400-500 Kt of wheat from Australia and Canada in recent weeks as hot and dry weather threatens to damage crops in China’s main wheat area (LSEG). The purchases from Australia were the first made by China from the country since last year.
Last Friday, the Grain Industry Association of Western Australia (GIWA) reduced its wheat planted area estimate in the state by 2.9%, due to dry conditions in some regions.
FranceAgriMer reported 69% of France’s winter barley crop was in good or excellent condition by 5 May, while spring barley was rated at 81%, both down 1% on the previous week.
The USDA's WASDE report released this evening has strong potential to impact the market, with a first look at 2025/26 estimates.
Rapeseed
Paris rapeseed futures in £/t (Nov-25)
In £/t terms, Nov-25 Paris rapeseed futures traded below the 20-day moving average but still well above the support level of £380/t last week (Friday to Friday). An RSI at 45, shows prices have remained relatively stable for now.
Market drivers
Rapeseed prices dipped slightly last week (Friday to Friday), with Paris futures (Nov-25) down €0.50/t to €475.75/t. The drop was mainly driven by weakness across the wider oilseed complex, though losses were limited by continued supply tightness and currency support.
Statistics Canada reported that canola (rapeseed) stocks fell to 5.9 Mt at the end of March, a 38.7% decline on the year. The reduction is due to strong export demand and growing domestic use, particularly from the renewable energy sector. News of tighter stocks has supported prices, with Winnipeg canola futures (Nov-25) rising by 2.0% over the week.
Chicago soyabean futures (Nov-25) made some recovery on Friday, buoyed by fresh optimism over US-China trade talks, and ended the week flat. Meanwhile, Chicago soyabean oil futures (Dec-25) fell by 0.8%. For most of the week, soyabean prices faced pressured from rapid planting progress in the US, weaker export sales, and expectations of a larger crop in South America.
The USDA’s weekly crop progress report released last Monday showed that US soyabean planting reached 30% completion by 04 May. This is ahead of the five-year average of 23% though just under the 31% forecast. Dry weather expected in the Midwest is likely to further support planting in the days ahead. However, export demand remains slow due to weak demand from China and strong competition from Brazil. US soyabean sales for the week ending 1 May came in at 376.7 Kt, down 12% on the week.
The Buenos Aires Grain Exchange has raised its forecast for Argentina’s 2024/25 soyabean crop to 50.0 Mt, up from 48.6 Mt previously, driven by improved yields. For comparison, the USDA’s current estimate is 49.0 Mt. In Brazil, farmers are expected to increase soybean plantings by around 500.0 Kha for the 2025/26 season, starting in September, according to Agroconsult.
Looking ahead, all eyes will be on the USDA’s WASDE report due, as well as the ongoing negotiations aimed at resolving US-China trade tensions.
Extra information
The UK-India trade deal has the potential to boost demand for UK malting barley at a time when domestic demand is falling. While tariffs on UK whiskey exports to India previously stood at 150%, under the new deal, this will be halved to 75%, and is expected to drop to 40% after 10 years.