
Northern Ireland weekly market report – 13 October 2025
Northern Ireland weekly market report – 13 October 2025
13 October 2025
Grains
UK feed wheat futures (Nov-25)
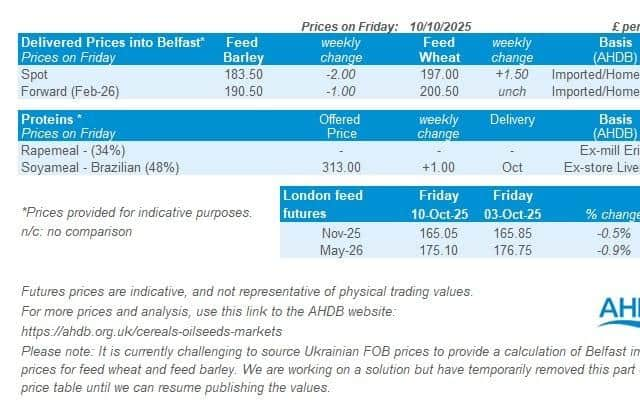

November 2025 UK feed wheat futures remained below the support level of £167/t last week (03 October – 10 October). In technical terms, a support level represents a price point where markets often find it harder to fall much further.
The relative strength index (RSI) edged downwards from 49 to 46, suggesting momentum slowed slightly on the previous week.
Market drivers
US and UK grain futures came under pressure again last week; ample supply and steady demand have damped market momentum and prices. UK feed wheat futures (Nov-25) finished the week at £165.05/t down £0.80/t (0.5%) on the week. Chicago wheat futures (Dec-25) closed 3.3% lower on the week. Broadly driving the pressure on global grain markets was on-going harvest pressure as US maize harvest continues and beneficial rains in Brazil that will aid plantings for maize crops. The Paris milling wheat market marginally gained on the week as the euro weakened against the US dollar.
Due to the US government shutdown, the market was absent last week from receiving the USDA reports, notably the October World Agricultural Supply and Demand Estimates and the weekly Crop Progress report. With the absence of this data, in a Reuters poll of nine analysts estimated that the US maize crop was 29% harvested by Sunday (05 Oct), up from 18% the previous week but behind the year-ago pace of 30% (LSEG). It’s worth noting that this is just a poll and not the official data, usually published by the USDA. Weather has been favourable over the main maize regions over the last week and looks to continue into the coming week suggesting progress will continue to move well.
In the EU, Expana raised its soft wheat output by 0.3 Mt from last month's forecast to 136.4 Mt, up 22.8 Mt from the rain-affected 2024/25 crop, projecting a record high wheat crop as well as 17-year high for the barley crop. The maize crop was also raised by 0.8 Mt to 56.5 Mt, after the harvest turned out slightly better than previously expected but is still the second lowest since 2007.
Russian consultancy group Sovecon raised its forecast for the country’s wheat crop in 2025 to 87.8 Mt, up from a previous forecast of 87.2 Mt, with record yields recorded in parts of Siberia. Export estimates have also been raised with September up by 0.3 Mt tons to 4.6 Mt with forecasts of 5 Mt in October.
Argentina’s Rosario grain exchange increased its wheat harvest estimates to 23 Mt, citing good moisture and higher than expected yields. This estimate comes in 1.0 Mt higher than estimates from Buenos Aires grain exchange (22.0 Mt) reported in last week’s arable market report.
Rapeseed
Paris rapeseed futures in £/t (Nov-25)
Over the last week (03 – 10 October), Paris rapeseed futures (in £/t) bounced off the support level of £400/t, finishing slightly below the 20-day moving average.
The relative strength index (RSI) showed a fall in market momentum fell from 51 to 47 over the week. However, there is no clear indication of the direction of future price movements.
Market drivers
The oilseed market has been volatile over the past week due to the weaker euro against the US dollar, as well as unpredictable demand for US soyabeans from China. Paris rapeseed futures (Nov-25) rose by €8.50/t (1.9%) to €466.50/t on the week. However, the futures market of the 2026 crop (Aug-26) was limited, only increasing by only 0.3% to €456.50/t. Consequently, the price difference between the 2025 and 2026 contracts is €10.00/t from nearby to harvest.
The European Commission published that, by 05 October, rapeseed imports for the 2025/26 season, which began in July, had reached 1.03 Mt, against 1.46 Mt a year earlier. The main countries from which the EU imports rapeseed in the current season are Ukraine (58%), Moldova (19%), Australia (13%) and Serbia (8%).
Chicago soyabeans futures (Nov-25) fell by 1.1%, while Winnipeg canola futures (Nov-25) slightly rose 0.4% on the week.
Chicago soyabean futures started last week strong amid optimism about the US-China trade deal. However, after President Trump posted on Friday in response to China's export controls on rare earth minerals, he suggested that he may not meet with President Xi in South Korea later this month. According to China's General Administration of Customs, the world's top soybean buyer imported 12.87 Mt in September, up 13.2% from 11.37 Mt a year earlier. Most of these imports in September are expected to have come from Brazil.