
Northern Ireland weekly market report - 17 November 2025
Northern Ireland weekly market report - 17 November 2025
17 November 2025
Grains
UK feed wheat futures (May-26)

UK feed wheat futures (May-26) traded below the 20-day simple moving average last week (07–14 November), but held above the support level of £173/t.
The relative strength index (RSI) eased to 56 from 62 the previous week, indicating a slowdown in market momentum.
Market drivers
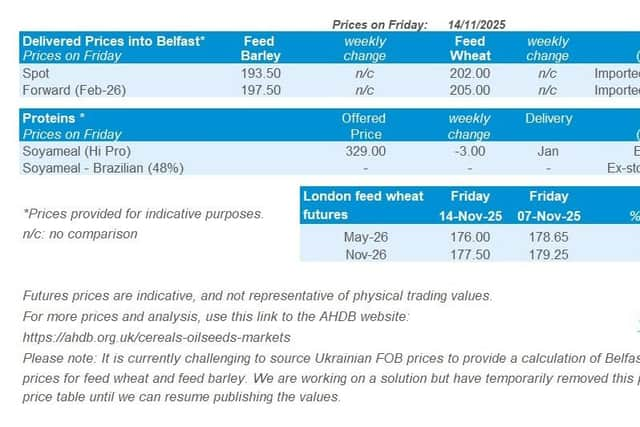
UK feed wheat futures eased last week, with the May-26 contract closing at £176.00/t on Friday, down £2.65/t (1.5%). This mirrored declines in Paris milling wheat futures, with the May-26 contract decreasing by 1.6%. Pressure on European prices stemmed from continued strong competition from Black Sea origins, ongoing harvest progress in Argentina and Australia, and a firmer euro against the US dollar, which ended the week at €1 = $1.1620. Meanwhile, Chicago wheat futures (May-26) modestly gained 0.1%, likely driven by speculative positioning. Overall, global wheat prices remain under pressure amid expectations of abundant supply.
On Friday, the USDA released its first World Agricultural Supply and Demand Estimates (WASDE) report since September, following the end of the 43-day US government shutdown. The 2025 US maize yield was reduced slightly to approximately 11.7 t/ha, with production revised down to 425.5 Mt, above the average analyst estimate of 420.6 Mt. A Reuters poll of nine analysts estimated the US maize harvest at 92% complete, slightly behind the USDA’s figure of 95% at the same point last year. The USDA’s weekly export sales reporting has resumed, with two catch-up reports per week until 08 January to publish previous weeks data.
Globally, the WASDE report confirmed a more bearish outlook for wheat. World production is forecast at 828.9 Mt, up 12.7 Mt from September, led by increases in Argentine (+2.5 Mt) and the European Union (+2.2 Mt). The global wheat stocks-to-use ratio, excluding China, is at its highest level since 2021/22, highlighting ample supply and continued price pressure.
In South America, Argentina’s wheat harvest (to 12 Nov) is around 15% complete. The Rosario Grain exchange now forecasts a record 2025/26 crop of 24.5 Mt (+1.5 Mt from last month), while the Buenos Aires Stock Exchange has raised its estimate to 24.0 Mt, up from 22.0 Mt previously. In Brazil, planting of the first 2025/26 maize crop was 85% complete in the centre-south region as at last Thursday (AgRural). Conab projects total maize production at 138.8 Mt, well above the USDA’s 131.0 Mt, which remained unchanged from September.
In Europe, Expana raised its EU soft wheat forecast by 0.4 Mt to a record 136.8 Mt, up 21% on last season. Barley output was increased to 56.6 Mt, with strong yields in Romania, Bulgaria, Poland and Scandinavia. In France, 98% of soft wheat is rated good or excellent as sowing nears completion (FranceAgriMer).
Rapeseed
Paris rapeseed futures in £/t (May-26)
In £/t terms, May-26 Paris rapeseed futures increased (7 November – 14 November), closing again above the 20-day moving average near £422/t. The 20-day moving average could be the nearest potential support price level.
The relative strength index (RSI) rose from 68 to 76, indicating an increase in market momentum and signalling a move back into the overbought zone, attention must be paid to the markets at this time.
Market drivers
There was marginal gains in the oilseed complex over the last week. Paris rapeseed futures (May-26) gained €0.25/t week-on-week, closing Friday at €477.25/t. The market digested the latest USDA World Agricultural Supply and Demand Estimate (WASDE) report last Friday, after the longest government shutdown in US history, key oilseed insights from the reports include:
Total world production of oilseeds has been revised down 3.5Mt for 2025/26 to 688Mt, but still above last year’s figure. Driving some of this was reduction to US’ output.
US soyabean production is estimated at 1.3 Mt lower than projected in September at 115.8 Mt, this is from lowered yields, this drop was higher than market expectations.
There were reductions to US soyabean exports (-1.4Mt) due to lower supplies and higher exports from Brazil (+500Kt) and Argentina (+2.25Mt).
Increases in global production for rapeseed at 92.3Mt (+1.3Mt), with increases to EU-27 (+500Kt), Ukraine (+300kt) and Australia (+300Kt) largely contributing to the increase. Although this is offset by lower opening stocks at 9.8 Mt (-0.5Mt), leaving ending stocks for 2025/26 near unchanged.