
Northern Ireland weekly market report - 27 May 2025


Northern Ireland weekly market report - 27 May 2025
27 May 2025
Grains
UK feed wheat futures (Nov-25)
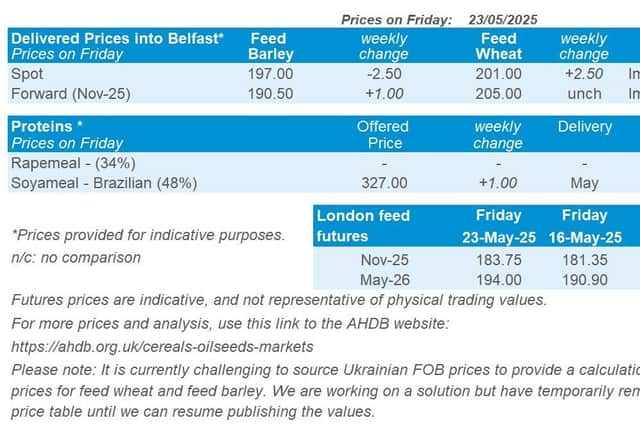
Nov-25 UK feed wheat futures gained last week (Friday–Friday), crossed the 20-day moving average and is attempting to stabilise near it. The relative strength index (RSI) at 52, up from 42 the previous week, suggests prices could find some relative stability.
Market drivers
UK feed wheat futures (Nov-25) increased by £2.40/t (1.3%) last week (16–23 May), closing at £183.75/t on Friday. Domestic prices followed global markets up, with Chicago wheat and Paris milling wheat futures (Dec-25) rising by 3.6% and 1.5% respectively.
Last week, concerns about weather risks in the US, northern Europe, China and Russia helped to push up the price of global wheat futures. Additionally, the funds have high levels of net short positions in Chicago and Paris contracts, supporting prices when these positions were covered last week.
The UK's domestic wheat futures could come under pressure compared to the global market in the near future, due to sterling strengthening against the US dollar (three-year high) and the euro (seven-week high).
The EU’s crop monitor MARS increased its forecast for the average soft wheat yield in 2025 to 6.04 t/ha, from last month's projection of 6.03t/ha. It is above the five-year average of 5.77t/ha. The report reveals that while some regions are facing drought challenges, favourable weather conditions are benefiting others.
FranceAgriMer estimated that 71% of French soft wheat was in good or excellent condition as of 19 May, down from 73% the previous week. For winter and spring barley, crops rated as good or excellent fell by 2% and 6%, respectively.
Last week, the USDA reported a decrease in winter wheat conditions in the US, with 52% rated as in good or excellent condition as of 18 May, compared to 54% the previous week.
The Rosario Grains Exchange is forecasting that the 2025/26 wheat harvest in Argentina could be the second largest on record at 21.2 Mt, given favourable weather forecasts and ideal soil conditions for planting.
The IGC left its forecast for global wheat production in 2025/26 unchanged at 806 Mt, while increasing its forecast for global maize production to 1 277 Mt, up 3 Mt from April. However, the IGC showed a decrease in the forecast global consumption of wheat and maize, both by 1 Mt.
Rapeseed
Paris rapeseed futures in £/t (Nov-25)
Nov-25 Paris rapeseed futures (in £/t) traded between the resistance level and the 20-day moving average last week. A small week-on-week rise in RSI (52 vs 49) suggests slightly stronger momentum.
Market drivers
Global oilseed markets edged up last week (Friday-Friday). Paris rapeseed futures (Nov-25) rose €4.25/t to €492.25/t. Chicago soyabeans, soyabean oil and Canadian canola also posted weekly gains, driven mainly by weather concerns in Argentina, strong US export demand and tight Canadian canola stocks.
In Argentina, heavy rainfall in northern Buenos Aires raised concerns about flooding and further delays to soyabean harvest, which is already behind schedule. As at 21 May, 74.3% of the crop had been harvested, compared to 87.9% at the same point last year (Buenos Aries Grain Exchange). However, drier weather is forecast in the coming days, which may ease concerns.
US soyabean net export sales for 2024/25 season reached 307.9 Kt in the week ending 15 May, up 9% from the previous week and above the range of analysts’ estimates. Soyabean oil sales also rose slightly week-on-week to 13.7 Kt.
In Canada, tight canola (rapeseed) supplies and strong export demand pushed Winnipeg canola futures (Nov-25) up 2.2% over the week. Canadian rapeseed exports have reached 8.19 Mt so far in the 2024/25 marketing year, compared with 5.14 Mt last year.
In Europe, LSEG raised Ukraine’s 2025/26 rapeseed crop forecast to 3.25 Mt, up 1.5% from its last estimate, due to recent rains, though this is still below the 2024/25’s output. Germany reports a 1.5% rise in the winter rapeseed area for 2025/26 to 1.1 Mha, according to the national statistics agency. Meanwhile, EU crop monitor MARS revised its 2025 EU-27 rapeseed yield forecast slightly lower to 3.17 t/ha, now aligning with the five-year average.
Looking ahead, markets are closely monitoring the possible 50% US import tariff on EU goods, now delayed to July.