
Northern Ireland weekly market report - 30 June 2025
Northern Ireland weekly market report - 30 June 2025
30 June 2025
Grains
UK feed wheat futures (Nov-25)

UK feed wheat futures fell last week (Friday to Friday), crossing below the 20-day moving average and approaching the strong support level of £175/t once again.
Market drivers
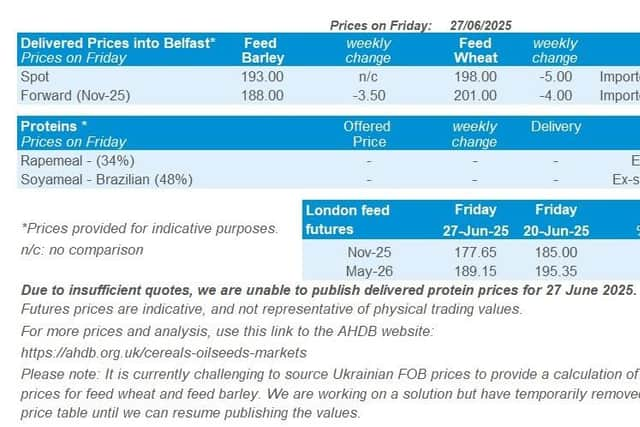
UK feed wheat futures (Nov-25) decreased last week (20–27 June), falling by £7.35/t (4.0%), to close at £177.65/t on Friday. Chicago wheat and Paris milling wheat futures (Dec-25) fell by 7.1% and 5.2% respectively.
Global wheat futures are under pressure due to the harvesting progression in the Northern Hemisphere and low export activity, particularly in the US. Also, speculative traders in Chicago wheat futures reduced their net short positions in the week ending 24 June, helping reduce the pressure on Chicago prices. An additional factor putting pressure on Paris futures was the stronger euro against the US dollar.
In a monthly update, the International Grains Council increased the global wheat production forecast by 2.3 Mt to 807.9 Mt. Conversely, maize production was decreased by 1.1 Mt. The increase in wheat production largely reflects higher production in India and Romania, while the forecast for maize production fell due to lower estimates for production in Ukraine.
Last Monday, the European crop monitor MARS increased its yield forecasts for wheat and barley in the EU by 1% and 2%, respectively, compared to the previous month, while leaving its maize estimates unchanged. This is putting pressure on the European wheat market, which is also weighing on the UK domestic market.
Last week, there was a lot of information about wheat crop prospects for the Black Sea region in 2025. A production estimate for Ukraine was decreased due to unfavourable weather conditions, while the production forecasts in Romania, Bulgaria and Russia improved.
According to StatsCan, the area of Canadian wheat in 2025 is 1.0% higher than the 2024 figures, while the area of barley fell by 4.2%. However, the area of wheat in 2025 is less than farmers had intended in March.
Brazil has approved increases in the percentages of ethanol and biodiesel blended into gasoline and diesel, from 27% to 30% and from 14% to 15% respectively. This is significant for maize, given the growing trend of using this crop to produce ethanol in Brazil.
Futures prices are indicative, and not representative of physical trading values. The latest daily futures settlement prices are available on our website.
Rapeseed
Paris rapeseed futures in £/t (Nov-25)
Nov-25 Paris oilseed futures (in £/t) fell back last week and ended the week below the 20-day rolling average after holding above it for much of June. The relative strength index (RSI) level also dropped from 70 to 58.
Market drivers
Oilseeds markets fell back last week after a level of volatility midweek. The easing of geopolitical tensions reduced concerns over energy supply disruptions, prompted a parallel pullback in vegetable oil-linked commodities.
Currency movements added another layer of pressure. The euro strengthened to $1.1719, its highest level since September 2021 (LSEG), reducing the competitiveness of euro-denominated oilseed exports and contributing to a correction in Paris rapeseed futures.
After reaching their highest level since July 2023 of €512.00/t on Friday 20 June, Paris rapeseed futures (Nov-25) prices retreated last week. Paris rapeseed futures (Nov-25) fell back €25.75/t (-5.0%) Friday – Friday, to close at €486.25/t. Chicago soybean oil futures (Dec-25) fell 4.5% over the same period, with Winnipeg canola (Nov-25) decreasing 6.7%. Nearby Brent crude oil futures fell 12.0% last week to $67.77/barrel.
In the US, warm, consistent rainfall and moderate temperatures across key US Midwest states have supported crop emergence. This is bolstering expectations for soyabean and maize yields.
In Canada, StatsCan estimated the 2025 canola (rapeseed) planted area at 8.7 Mha, a 2.5% decline from last year. The soyabean area has risen to 2.3 Mha, up 0.5% year-on-year.
While the areas came as traders expected, an upwards revision in last year’s canola production number was unexpected.
Indicating healthier stocks, production for 2024 was revised to 19.2 Mt, an increase of 7.9% on the previous figure.
Ukraine’s rapeseed production is forecast at 2.9 Mt by private analysts, down from 3.7 Mt in 2024, while soybean output is expected to fall 0.4 Mt year-on-year to 6.1 Mt.