
Northern Ireland weekly market report – 31 March 2025
Northern Ireland weekly market report – 31 March 2025
31 March 2025
Grains
UK feed wheat futures (May-25)

With May-25 UK feed wheat futures closing below the recent support levels for three consecutive weeks, the previous support and resistance levels no longer hold. With the Relative Strength Index (RSI) in the oversold zone, prices could now find support around £163/t.
Market drivers
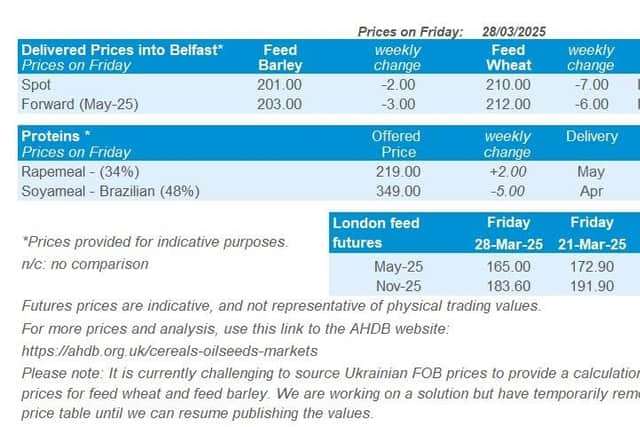
UK feed wheat futures (May-25) dropped to a new low last week (Friday to Friday), ending at £165.00/t, down £7.90/t from the previous week. The Nov-25 contract fell £8.30/t, settling at £183.60/t on Friday.
Domestic wheat markets tracked the global price decline, with pressure from ongoing negotiations surrounding the Ukraine war, favourable weather forecasts in key producing regions, and weak global export demand.
Ongoing talks, brokered by the US, for a ceasefire between Russia and Ukraine are impacting market direction at the moment. While the resumption of the agreement to ensure safe passage for ships in the Black Sea is uncertain, news of a potential resolution is putting pressure on wheat prices.
Beneficial rainfall is forecast for key producers, including the US, Russia, Romania, and Bulgaria. Following dry conditions, the rain is expected to ease concerns about crop stress and improve the outlook for harvest.
US wheat export sales for the week ending 20 March were reported at 100.3 Kt, down from 248.8 Kt last week and 65% lower than the four-week average. Net export sales of maize also fell to 1.03 Mt, remaining unchanged from the prior four-week average.
Chicago wheat speculators increased their net short position in futures and options contracts to 92,587 as at 25 March. This suggests that the speculators are anticipating falling wheat prices.
Russia's IKAR consultancy has increased its 2025 wheat crop forecast to 82.5 Mt, up from 81.0 Mt, due to better weather conditions for the winter crop.
Later today (31 March), the USDA will release its quarterly stocks and planting intention reports. Expectations point to a year-on-year rise in wheat stocks and maize planting intentions.
Meanwhile, further developments are expected regarding the US tariffs on Canada, Mexico, and China, which take effect on 2 April.
Rapeseed
Paris rapeseed futures in £/t (May-25)
A rally in May-25 Paris rapeseed futures, saw prices climb firmly above the 20-day moving average last week (Friday to Friday). The price chart shows that futures may find a resistance level at £452/t.
Market drivers
May-25 Paris rapeseed futures closed at £438.05/t on Friday, up £24.25/t on the week. New crop (Nov-25) futures finished on Friday at £407.83/t, up £9.95/t. The spread between old crop and new crop rapeseed prices widened again.
Old crop Paris rapeseed futures rose last week, mainly due to limited supply in the EU physical market. For new crop futures, good winter crop conditions and favourable weather forecasts limited support.
Winnipeg canola futures (May-25) gained by 7.3% over the last week (Friday to Friday). However, the canola market is awaiting news on US tariffs. The spread between Paris rapeseed and Winnipeg canola futures could encourage more canola imports from Canada into the EU.
May-25 Chicago soyabeans and soyabean oil futures rose 1.3% and 7.5% respectively (Friday-Friday). US net export sales of soyabeans were reported at 339 Kt by the USDA for the week ending 20 March, lower than the previous week and at the low level of trade estimates. For soyabean oil, US net export sales were higher than estimated and this supported soybean prices late last week.
A positive factor for Chicago soyabean oil could be a higher biodiesel blend in the US, which is currently under discussion.
Today, the USDA's prospective plantings and grain stocks reports will be published, which could have a significant impact on prices and will be a key focus for market participants.
Palm oil prices have been affected by lower production and export demand, resulting in higher ending stocks. The nearby Malaysian palm oil futures are currently higher than next month’s, meaning that global oilseeds could see some pressure over coming months from these heavy supplies.