
Northern Ireland weekly market report - 6 May 2025
Northern Ireland weekly market report - 6 May 2025
6 May 2025
Grains
UK feed wheat futures (May-25)
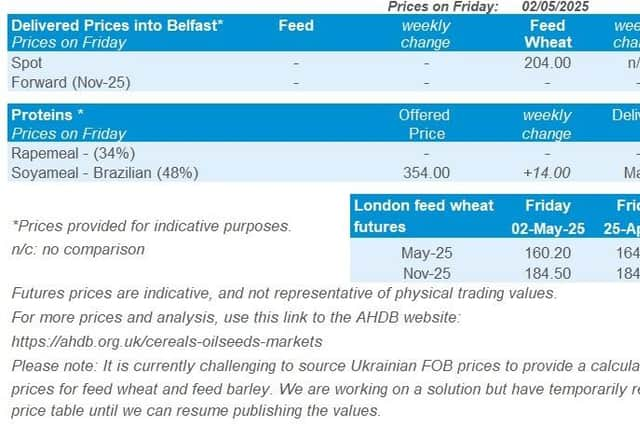

May-25 futures held above the recent support level of £160/t last week. With the RSI at 40, this could offer some support to old crop futures prices. However, the May-25 contract’s value as a market indicator is decreasing as it enters its final weeks of trading. From next week, we’ll report on the Nov-25 prices here.
Market drivers
Global wheat futures prices lost more ground last week and again yesterday. Forecasts of rain in the US winter wheat areas and improving crop conditions weighed on prices in the early part of the week.
Old crop prices also had pressure from uncertainty over global demand and technical trading as the May futures contracts approach expiry. UK feed wheat futures for May-25 reached a new contract low of £160.00/t on Thursday and ended the week at £160.20/t, down £4.70/t from 25 April.
However, the Nov-25 contract ended the week down just £0.35/t at £184.50/t after partially rebounding on Friday. The market was supported on Friday by “bargain buying” in Chicago futures (LSEG).
Yesterday, falls in wider markets including crude oil, confidence in US crops and forecasts of rain for Black Sea crops pushed global wheat prices lower. Dec-25 Paris wheat futures lost a further €4.25/t to close at €212.50/t and Chicago Dec-25 wheat futures declined $3.95/t to $208.68/t.
Dry weather is a growing concern across Northern Europe, but markets are currently focusing on the improved weather outlook for 2025/26 US and Black Sea crops.
Last night, the USDA reported that US maize planting was 40% complete by 4 May, up from 24% a week earlier. Also, the proportion of US winter wheat in good or excellent condition rose week-on-week from 49% to 51%, now the highest rating since 2020.
This morning, Russian consultancy IKAR increased its 2025 production forecast by 1.3 Mt to 83.8 Mt, now 1.4 Mt above the 2024 crop.
Market attention will increasingly focus on Monday night (12 May), when the USDA will release its first estimates of global supply and demand in 2025/26. The forecasts can influence market sentiment in the weeks and months that follow.
Futures prices are indicative, and not representative of physical trading values. The latest daily futures settlement prices are available on our website.
Rapeseed
Paris rapeseed futures in £/t (Nov-25)
Nov-25 Paris rapeseed futures in £/t continued to trade around the 20-day moving average last week, suggesting a period of price stability as recent resistance and support levels hold steady.
Market drivers
Nov-25 Paris rapeseed futures ended the week up €2.00/t (Friday-Friday), closing at €476.25/t. The main driver was a weaker euro against the US dollar, which helped increase the competitiveness of EU exports. This came despite the broader oilseeds complex ending the week lower.
Chicago soyabean futures (Nov-25) lost 0.4% over the week, due to the advancing harvest in South America and concerns about global demand amid the ongoing US–China trade war. Technical buying towards the end of the week helped limit the losses, but underlying fundamentals remain weak.
China is reportedly looking to reduce soyameal use in livestock feed to 10%, to cut its reliance on US soyabean imports. There is still no clarity on potential negotiations between the two parties.
Despite harvest delays due to heavy rainfall and uncertainty around export policies and exchange rates, Argentine farmers made their biggest one-day soyabean sales of the year last week, according to the Rosario Grain Exchange. As of 29 April, harvest progress stood at 24%, down from 36% at the same time last year (Buenos Aries Grain Exchange). However, dry weather forecast for the coming week could accelerate progress.
US soyabean export sales totalled 428.2 Kt for the week ending 24 April, falling within analysts’ expectations of between 150 Kt and 600 Kt. This offered some support despite the broader demand concerns.
Rapeseed imports into the EU continue to rise due to tight domestic supplies. The EU Commission shows season-to-date imports at 5.55 Mt, up 15% year-on-year. Looking ahead, production prospects are improving. LSEG has revised its 2025 forecast for the EU-27 plus the UK crop up by 1.8% to 20.2 Mt, due to improved weather conditions.
In Ukraine, the sunflower area for 2025 is expected to grow by 5% from 2024, according to the Ukrainian Agribusiness Club (UCAB). In addition, consultancy APK-Inform forecasts the 2025 sunflower harvest to rise by 14% year-on-year, projecting a total of 15.2 Mt.
Futures prices are indicative, and not representative of physical trading values. The latest daily futures settlement prices are available on our website.