
Northern Ireland weekly market report: 9 December 2025
Northern Ireland weekly market report: 9 December 2025
9 December 2025
Grains
UK feed wheat futures (May-26)

Last week, UK feed wheat futures (May-26) finished below the 20-day average but above the support level of £167/t.
The relative strength index (RSI) eased to 27 from 32 the previous week, indicating a significant decrease in price. RSI is now approaching the oversold zone.
Market drivers
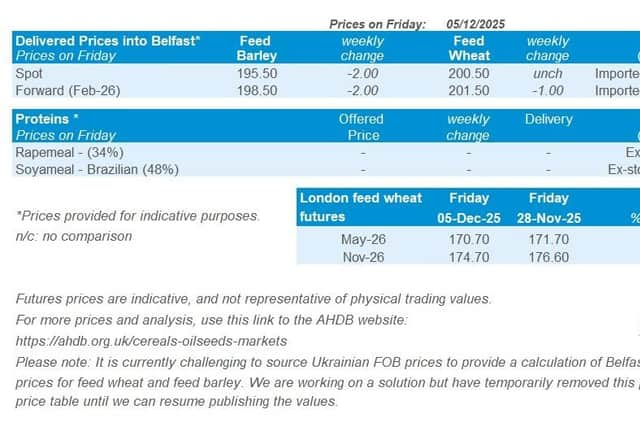
UK feed wheat futures fell over last week (28 November – 05 December). The May-26 contract closed at £170.70/t down £1.00/t (0.6%) on the week, setting a new contract low. Chicago wheat futures broadly ended down, while Paris milling wheat ended mixed but hovering around contract lows.
The domestic market was weighed on by currency movements and strong production statistics released last week from Canada and Australia, adding to what is already a sizable year for global production of grains. Sterling reached its strongest against the euro and the dollar for just over a month last week, ending Friday at £1 = €1.145 and $1.333, respectively.
The final 2025 production of principal field crops report was released in Canada, total wheat production (inc. Durum) was revised upwards for 2025 to 39.9Mt, this is up 11.2% year-on-year (StatsCan). The total wheat figure surpassed an average Reuters poll (LSEG survey based on seven analysts), which estimated the crop at 38.5Mt, adding to global supplies for 2025/26.
In Australia, the Australian Bureau of Agricultural and Resource Economics and Sciences (ABARES) released its crop report for December. Australia’s winter crop production is expected to increase by 10% to 66.3 Mt in 2025/26, the second largest winter crop on record. Wheat output is forecast at 35.6 Mt against 33.8 Mt in September estimates (USDA 36 Mt). Barley has been revised to 15.7 Mt up 1.1 Mt from September (USDA 15.0 Mt). Some of this increase was expected given the better-than-expected growing season in Western Australia.
Some tensions persist in the Black Sea region. Russia threatened Ukraine’s access to the Black Sea after drone attacks on Russian vessels last week. The threat unsettled grain markets and have buoyed some prices as war-risk premium was built in, this soon subsided, but this is a key watchpoint for grain prices going into 2026.
Rapeseed
Paris rapeseed futures in £/t (May-26)
In £/t terms, May-26 Paris rapeseed futures decreased last week (28 November – 05 December), and closed below the 20-day moving average near £411/t. The RSI fell from 45 to 37, signalling weaker momentum as it moved closer to the oversold zone.
Market drivers
Global oilseed markets weakened last week, with Paris rapeseed futures (May 26) falling by €7.50/t (1.6%) to €471.25/t. This pressure is filtering into UK prices, with domestic rapeseed values easing in line. Chicago soyabean and Winnipeg canola futures also dropped, reflecting ample global supplies.
China’s slower pace of US soyabean purchases continues to weigh on market sentiment. Although the USDA confirmed a further 462 Kt sale last week, total reported volumes of 2.7 Mt since 30 October from the USDA’s daily reporting system, demand remains below expectations. This uncertainty over the scale and timing of Chinese demand keeps global soyabean markets pressured and reverses the premium that has been built in, which in turn limits support for UK rapeseed prices.
South America remains a key driver of global supply. Brazil’s 2025/26 soyabean crop forecast has been slightly reduced to 177.2 Mt in December, down from 178.9 Mt last month, due to uneven rainfall, though expectations still point to a record harvest (StoneX). Planting is nearly complete, with 91% of the area sown, slightly behind last year’s pace but finished in key states including Mato Grosso, Mato Grosso do Sul and Paraná (Patria Agronegocios). In Argentina, 2025/26 soyabean planting lags due to recent rains limits access to fields, although crop conditions remain mostly good (Buenos Aires Grain Exchange).
Elsewhere, the Australian Bureau of Agricultural and Resource Economics and Sciences forecasts 2025/26 canola production at 7.2 Mt, up 1.2 Mt (13.1%) on last year, while the USDA estimates 6.7 Mt.
In Canada, Statistics Canada projects a record 21.8 Mt canola crop for 2025/26, 13.3% higher year-on-year and above analysts’ expectations of 21.25 Mt, supported by timely summer rainfall that boosted yields across the Prairies. Canadian canola is currently subject to significant tariffs in China, restricting access to this key market and contributing to larger supplies globally.