
Northern Ireland Weekly Report - 8 July 2024
Northern Ireland Weekly Report - 8 July 2024
Grains
Wheat
Crop harvests in the Northern Hemisphere are moving quickly, bringing new supplies onto the market. Expectation of smaller crops globally this year still persist however demand is also expected to remain high.

Maize
The second maize harvest in Brazil and crop conditions in the US and the Black Sea remain key focus in the short term. More US acreage than expected (reported last week) remains a factor for markets as it suggests there will be plenty of global supplies in the longer term.
Barley
Global barley supplies are expected to increase annually in 2024/25. Feed barley prices are projected to align with trends in the broader grains market, although harvest outcomes in key producing countries may also play a role.
Global markets
After declining prices through much of June, global wheat markets saw a gain last week. The Dec-24 Chicago wheat and Paris milling wheat contracts were up 2.8% and 1.5% respectively over the week. Chicago maize also rose on concerns over dry, hot weather disrupting the US crop during its crucial growing period. Specifically, the Dec-24 contract was slightly up 0.8% on the week.
The US winter wheat harvest is progressing quickly, at 54% complete as at week ending 30 June (USDA), well ahead of the five-year average of 39% for this point in the season. Meanwhile, 67% of the US maize crop was in a good or excellent condition. This was down 2% from the prior week following recent flooding.
Russian consultancy, SovEcon, revised its forecast for the Russian 2024/25 wheat crop from 80.7 Mt to 84.1 Mt due to favourable weather conditions and high yields in the South.According to Agribusiness consultancy, AgRural farmers in Brazil have harvested 65% of the second maize crop in key southern regions of the country. Globally this crop is counted as part of the 2023/24 crop year. This was up from 49% in the previous week and 26% at a similar time last year. Brazil is a major producer of maize globally and the second or “safrinha” maize crop makes up about 75% of the country’s total production annually.
UK focus
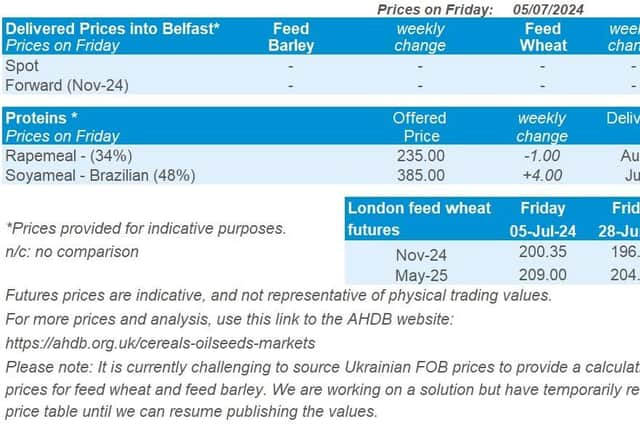
Domestic wheat futures followed global price movement up last week. Nov-24 UK feed wheat futures closed on Friday at £200.35/t, up £4.35/t on the week. The May-25 contract rose £5.00/t over the same period, ending Friday’s session at £209.00/t.Domestic delivered feed wheat prices followed futures up Thursday - Thursday. Feed wheat delivered into East Anglia for November delivery was quoted at £197.50/t on Thursday, up £1.00/t on the week. Delivered bread wheat into North-West for harvest delivery was quoted at £274.50/t on the week with no price comparison.
In the latest UK human and industrial cereal usage, flour millers processed a total of 5.7 Mt of wheat from July 2023 to May 2024, up by 3.4% from the previous year. This total consists of 4.6 Mt domestically milled wheat and 1.1 Mt of imported wheat. Flour production reached 4.5 Mt, a slight rise of 1.9% compared to previous year’s figure.
In May 2024, GB animal feed usage increased by 2.5% compared to April but saw a slight year-on-year decrease of 0.3%.
However, there were year-on-year rises in cattle and calf feed production, compounds for breading sheep and pig growing compounds.
The results of AHDB’s Planting and Variety Survey were released on Friday, providing cereal estimates for the upcoming harvest. Based on the data, the UK wheat area is estimated to reach 1,560 Kha in 2024, down 9% from last year.
This is the second smallest area since 1981, after 2020. The total barley area is also up 6%, with the oat area up 9% due to a rise in spring cropping. Crop conditions also improved between the end of May and the start of July, but they remain well below last year’s levels.
Oilseeds
Rapeseed
Concerns regarding production following poor early harvest reports in Eastern Europe supported the rise in rapeseed prices last week, in addition to considerable strength in soyabean oil futures. Future harvest results will need to be watched closely.
Soyabeans
Ample production forecasts continue to weigh longer-term. But, as the US soyabean crop transitions into its next growth stages, weather remains a key watchpoint.
Global markets
Global oilseeds markets were supported over the week (Friday to Friday). Chicago soyabean futures (Nov-24) rose by $9.46/t to close at $415.07/t on Friday; the contract rose on each trading day. US markets were closed on Thursday for a public holiday (Independence Day). Chinese bargain buying of US soyabeans, weather concerns for key soyabean producing regions in the US, and a rally in soyabean oil futures supported the oilseeds complex.Analysts forecast Chinese purchasing of US soyabeans to rise significantly in July with estimates of 12 – 13 Mt.With the US soyabean planting campaign complete, market focus is drawn to the blooming and pod setting stages reported 20% and 3% complete respectively last Monday.
While US soyabean conditions scored 67% good or excellent, current stages of the crop’s development are more sensitive to weather conditions. Some weather forecasts for later July and early August predict dryness and high temperatures causing concern for pod setting.Argentina’s soyabean harvest is largely complete.Recent strength in Chicago soyabean oil futures has also contributed to the appreciation of oilseed futures. Soyabean oil futures were supported by China potentially increasing tariffs on Indonesian goods (e.g. palm oil) in response to an announced change to Indonesian trade policy, as well as increased biofuel production capacity in the US.
Rapeseed focus
Paris rapeseed futures gained on the week (Friday to Friday), as the Nov-24 contract rose by €28.50/t to close at €514.50/t. Early harvest results from key producers in Europe have been below market expectations, which supported prices.
Strength in Chicago soyabean oil futures also buoyed the vegetable oils complex.
Rapeseed delivered into Erith for August delivery was quoted at £415.50/t on Friday, rising £18.00/t on the week. Also, delivery into Erith for November was quoted at £426.50/t, gaining £19.00/t on the week.In the latest AHDB development crop report, 54% of winter OSR was rated good or excellent. While this is a five percentage point improvement from the previous report, it remains behind this time last year of 63% good or excellent.