
Northern Ireland weekly market report - 26 August 2025
Northern Ireland weekly market report - 26 August 2025
26 August 2025
Grains
UK feed wheat futures (Nov-25)
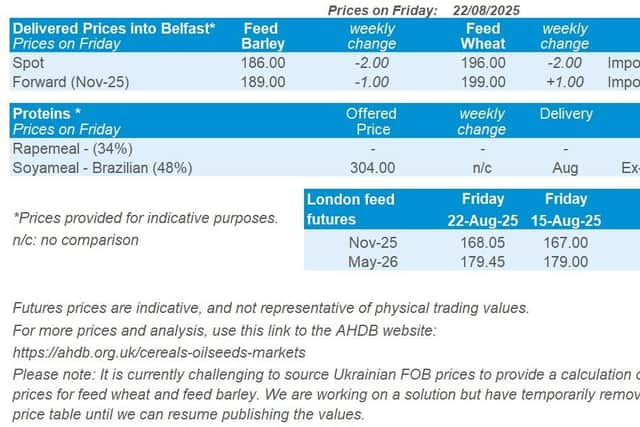

UK feed wheat futures edged higher last week (Friday to Friday), now just above the new ‘support level’ of £167/t, seemingly in line with Paris futures. When analysing price trends, a ‘support line’ is seen as a level that it may be harder for prices to fall below.
The relative strength index (RSI) rose slightly from 21 to 29, maintaining levels described as ‘oversold’ in technical analysis and showing the significant downward market momentum. An RSI at ‘oversold’ levels can also indicate this is a time to watch markets more closely.
Market drivers
UK wheat futures (Nov-25) gained last week, up £1.05/t (0.6%) closing at £168.05/t on Friday. A slight fall in the value of the sterling against the dollar £1 = $1.3411 (LSEG) on Thursday, as well as buyers repositioning after recent lows, helped prices gain on the week.
The IGC has raised it’s 2025/26 global wheat forecast to 811 Mt. Driven by improved crop conditions, adding 3 Mt to its previous estimate, signalling stronger supply potential heading into the new season.
In the United States, crop scouts on the Pro Farmer tour noted above-average yield potential in key states.
With Iowa, the top producing maize area in the US, seeing the highest yield potential in 22 years.
Maize production this season was estimated at 411.6 Mt (below USDA’s 425.3 Mt). Pro farmer added widespread southern rust and sudden death syndrome could trim final output.
In the EU, France has seen mixed quality in its wheat, with lower protein but strong milling indicators. 73% of soft wheat meets ≥11% protein (vs. 83% five-year average), but Hagberg falling numbers and specific weights are solid across the board.
France has seen a run of exports to Egypt, Tunisia, and Thailand, noting this is partly due to a slow start to Russia’s export campaign.
In Germany, the wheat harvest rebounds to 21.7 Mt, but rain has dented quality. Output is up 21.9% year-on-year after last season’s poor results.
However, persistent summer rain delayed harvest and reduced protein content and falling numbers.
The August MARS report sees expected wheat yield rise by 1% from the July report at 5.92 t/ha. Maize yields for Europe have been cut by 3% from the previous report to 6.93/t/ha, citing drought across the southeast of the continent.
In Russia, Sovecon revised wheat output upward to 85.4 Mt (+0.2 Mt) due to strong yields in Siberia and the Urals. Yet, logistical delays from inland regions to Black Sea ports are holding back early-season exports.
In Argentina, the Rosario exchange expects the wheat crop for 2025/26 at 20 Mt, 15.3% above the 5-year average, amid ideal planting conditions, abundant rainfall over recent months and less disease/pest pressure from the plague of leaf hopper bugs seen last season.
Argentina is also expected to see a near record planted area for maize at 7.8 Mha in 2025/26, up 9.6% on the year, and the second largest after the 8.4 Mha planted in 2023/24.
Futures prices are indicative, and not representative of physical trading values. The latest daily futures settlement prices are available on our website.
Rapeseed
Paris rapeseed futures in £/t (Nov-25)
Paris rapeseed futures (Nov-25) ended last week close to the 20-day moving average. Currently, the 20-day moving average is acting as a barrier to further increases in the price.
The relative strength index (RSI) decreased from 41 to 39 during the week (Friday-Friday), still indicating the lack of momentum as of late.
Market drivers
Paris rapeseed futures (Nov-25) increased last week, finishing at €475.50/t on Friday, up €1.75/t (0.4%) from the previous Friday.
During the week, Chicago soybean futures and Winnipeg canola futures (Nov-25) increased by 1.5% and 0.9%, respectively. Paris rapeseed futures (Nov-25) gained a further €1.75/t during yesterday's session, while domestic markets were closed.
Prices in the oilseeds complex were mainly supported last week by rising crude oil prices and the recent activation of 2025 soyabean exports from US.
However, any potential increase was limited by global supply, as well as geopolitical and economic unpredictability.
For rapeseed, the outlook for production in Canada and the restricted capacity to export to China limit any further potential increase.
Yesterday, the Monitoring Agricultural Resources (MARS) bulletin increased its forecast for European 2025 rapeseed yield, revising it upwards slightly from 3.20 to 3.24 t/ha.