
Northern Ireland weekly market report

22 April 2025
22 April 2025
Grains
UK feed wheat futures (May-25) remained within range of support and resistance levels last week and are trading back above the 20-day rolling average. A stronger relative strength index compared to last week also shows a slight uptick in market momentum.

Market drivers
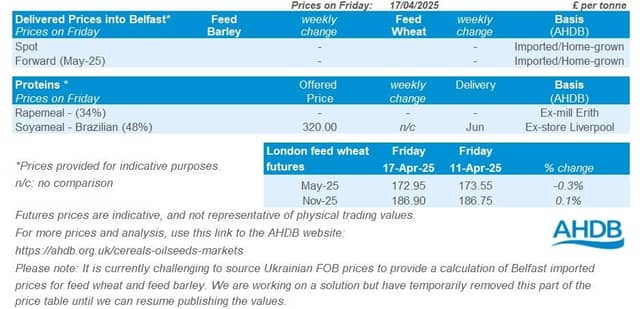
Last week, old crop (May-25) UK feed wheat futures fell £0.60/t (Friday – Thursday), to close at £172.95/t. While the new crop contract (Nov-25) gained £0.15/t over the same period, to end Thursday’s session at £186.90/t, extending its premium over old crop.
Old crop domestic prices followed bearish sentiment in the wider grains market last week. Chicago wheat (May-25) and Paris milling wheat (May-25) futures were down 1.3% and 3.2% respectively Friday to Thursday, with a strengthening euro against the US dollar and weak export demand contributing to greater pressure in European markets. New crop development driven by weather updates, currency fluctuations, and question marks over global export demand are in focus.
Following concern over dryness in the US, news of welcomed rain added bearish sentiment to US markets last week. However, while a proportion of the winter wheat crop benefitted from some rain, wet weather largely hit the US maize belt, leading to concern over delays in the planting of the spring crop. The impact of dry conditions for winter wheat remains in focus, with the USDA reporting 45% of the crop in good or excellent condition, down from 50% this time last year. With more rain forecast over the coming week, updates on winter crop conditions and spring plantings in the US could be a key price driver.
Ongoing peace talks between Russia and Ukraine remain a watchpoint. Sovecon analysts said that market optimism over a potential settlement of the war in Ukraine had seen Russian wheat export prices fall last week. Sovecon also increased its export estimate for April by 0.1 Mt to 2.0 Mt, though this stays considerably lower than April 2024 when Russian wheat exports totalled 5.0 Mt.
As Northern Hemisphere winter crops progress through their key development phase, updates on European crops are a key factor. FranceAgriMer said on Friday that 75% of the country’s wheat crop was in good or excellent condition by 14 April, up from 64% a year earlier. It is also estimated that 39% of France’s maize crop was planted by 14 April, versus 15% a week earlier.
Rapeseed
Paris rapeseed futures in £/t (May-25)
May-25 Paris rapeseed futures continued to trade above the 20-day moving average, following a strong rise from Friday to Thursday. The price chart has found a new resistance level at £550/t.
Market drivers
Paris rapeseed futures ended the week higher (Friday to Thursday) despite a stronger euro. The old crop (May-25) contract rose €12.50/t to €535.00/t, while new crop (Nov-25) gained €3.50/t to €479.50/t. The old crop premium to new crop extended to €55.50/t. Gains largely came from strength in the wider vegetable oil complex, with Chicago soyaoil and Winnipeg canola futures (May-25) both up 1.1%, alongside rising crude oil prices.
The National Oilseed Processors Association (NOPA) reported lower-than-expected soyaoil stocks as of 31 March. Stocks among NOPA members declined by 0.3% since the end of February, the first drop in six months, and were down 19.1% compared to the same time last year (LSEG).
Strong canola exports in Canada, despite trade tensions, are driving stocks lower and supporting prices. Last week, the Canadian Grain Commission reported season-to-date exports at 7.4 Mt, with 16 weeks left in the current marketing year. Currently, the USDA estimates total 2024/25 canola exports at 8.3 Mt.
Strong demand for rapeseed on the continent is also supporting markets. With a smaller EU supply this season, imports have been higher. As of 13 April, the EU Commission reported imports since July had reached 5.3 Mt, up from 4.6 Mt during the same period last year.
LSEG kept its 2025/26 rapeseed production forecast for the EU-27 + UK at 19.9 Mt. However, soil moisture levels remain low in key producing areas such as Poland and Germany.
Consultancy, APK-Inform, estimates that Ukraine’s 2025 rapeseed crop will fall to 3.39 Mt (USDA: 3.8Mt), down from 3.70 Mt in 2024, with exports likely to drop to 2.72 Mt from 3.14 Mt. However, the 2025 sunflower harvest is projected to rise by 14% to 15.2 Mt.
The French Farm Ministry raised its 2025 rapeseed area estimate to 1.29 Mha, up from 1.27 Mha.