
Northern Ireland weekly market report - 11 August 2025

Northern Ireland weekly market report - 11 August 2025
11 August 2025
Grains
UK feed wheat futures (Nov-25)
UK feed wheat futures continued to move lower last week (Friday to Friday), closing not far above the support level of £170/t. The relative strength index (RSI) eased from 47 to 36, reflecting a slowdown in market momentum.
UK Harvest Progress
AHDB’s third harvest report was released last Friday, showing crop progress up until 06 August 2025, the fifth week of the typical harvest period. The wheat harvest had reached 48% complete, ahead of the same point last year (37%) and well ahead of the five-year average of 31%.
Yields have improved since the last report to 7.66t/ha, 1% below the five-year average. Soil type has largely guided yields with significant regional and inter regional differences.
Quality this year is reported to be good, in Group 1 samples Hagberg falling numbers are generally above 300, protein samples are averaging 13.5% and moisture levels are coming in at 15% ranging from 12.2% to 17%.
Market drivers
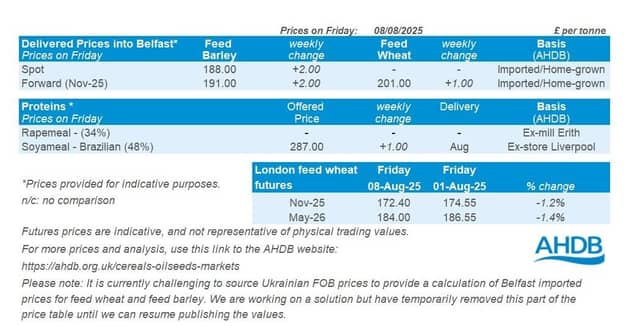
UK feed wheat futures (Nov-25) continued to fall last week, finishing at a contract low of £172.40/t on Friday and down £2.15/t (-1.2%) on the week.
Domestic feed wheat futures followed global markets, which were pressured by strong supply prospects, harvest progress and lacklustre export demand. Paris milling wheat and Chicago milling wheat (Dec-25) fell by 0.6% and 0.4% respectively.
Expana (formerly Strategie Grains) has raised its EU-27 soft wheat crop estimate by 2.1 Mt to 132.8 Mt for this season sighting good yield and quality for southern Europe. Prospects also remain positive in northern Europe despite concerns about grain quality.
With Paris wheat futures hitting contract lows last week financial investors trimmed their net short position. As these positions can be used to profit from falling markets, this suggests they’re slightly less convinced prices will keep falling.
In the US, harvest progress is weighing on markets amid ample global supply. Chicago Dec-25 wheat futures hit a new contract low last Tuesday, along with multiple other contracts. The fall in prices has stimulated demand though, with higher-than-expected weekly export sales.
As of the 03 August 86% of the winter wheat had been harvested in the US, down 1 percentage point compared to five-year average.
In Ukraine, APK-Inform cut its wheat harvest forecast by 900 Kt to 19.7 Mt, citing dry weather during key growth stages. Meanwhile, maize output has been revised upwards by 2.4 Mt to 27.1 Mt, thanks to improved yields in central and southern regions.
Futures prices are indicative, and not representative of physical trading values. The latest daily futures settlement prices are available on our website.
Rapeseed
Paris rapeseed futures in £/t (November - 25)
Last week (Friday–Friday), Paris rapeseed futures (in £/t) finished below the 20-day moving average again. However, the £400/t support level remains valid.
The relative strength index (RSI) increased from 45 to 46 during the week, indicating some price consolidation.
Market drivers
Paris rapeseed futures (Nov-25) fell last week to finish at €468.25/t down €6.75/t (1.4%) on the week (Friday-to-Friday). Winnipeg canola and Chicago soyabean futures (Nov-25) also fell during the week, by 1.9% and 0.2% respectively.
The global oilseed complex came under pressure due to favourable weather conditions in the US and Canada, high crop conditions scores for US soyabeans and falling crude oil prices. Furthermore, concerns over China's lack of purchases from the 2025 US soyabean crop so far put additional pressure on the market last week.
EU rapeseed imports in the 2025/26 season (which started on 1 July) had reached 0.26 Mt by 3 August, against 0.43 Mt a year earlier. Meanwhile, soyabean imports in the same period reached 0.97 Mt, compared with 1.30 Mt a year earlier.
APK-Inform has revised its forecast for Ukrainian rapeseed production in 2025 down from 3.2 Mt to 3.0 Mt. Sunflower seed production in 2025 was also cut by 5.5%, from 14.6 Mt to 13.8 Mt, due to poor weather conditions in the southern regions of the country.
As of 7 August, US net export sales for 2024/25 were 467.8 Kt, which was up 71% from the previous week and 63% from the prior four-week average. However, speculators increased their net short position in Chicago soyabeans in the week ending 5 August, which is putting pressure on the market in general.
China's soyabean imports reached a record high for July. Data from the General Administration of Customs showed that the world's largest soyabean importer brought in 11.7 Mt in July, up 18.5% from 9.9 Mt a year earlier (LSEG). Brazil actively exported soyabeans to China, while US soyabean exports were at risk due to concerns about unpredictability of tariffs. Malaysian palm oil futures came under pressure due to concerns about rising production and stock levels. Weak export demand also had a negative impact on the market.