
Northern Ireland weekly market report 12 January 2026
Northern Ireland weekly market report: 12 January 2026
12 January 2026
Grains
UK feed wheat futures (May-26)

UK feed wheat futures (May-26) closed again below the 20-day simple moving average at the end of last week, but remained above the nearest support level of £167/t.
The relative strength index (RSI) rose to 44 from 39 the previous week, suggesting that the price is consolidating before moving further.
Market drivers
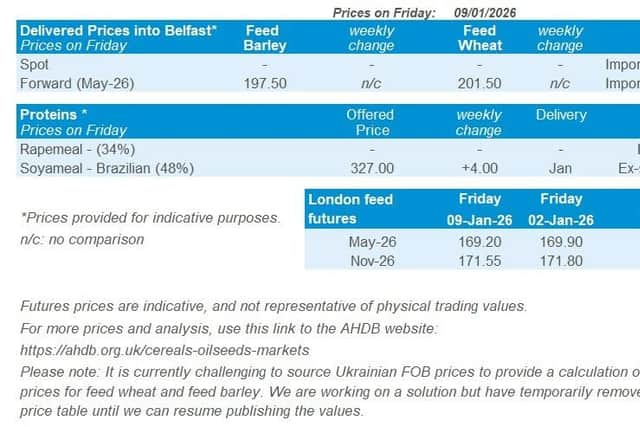
Despite firming global trends, UK feed wheat futures fell last week. Between 2 and 9 January, the May-26 contract fell by £0.70/t (0.4%) to close at £169.20/t. Meanwhile, Chicago wheat and Paris milling wheat futures (May-26) rose by 2.0% and 0.9% respectively. Last week, concerns about the dry weather affecting winter wheat in the US and Russia's attacks on Ukrainian infrastructure supported the global wheat market.
For the 2026 crop, UK feed wheat futures (Nov-26) fell by £0.25/t to £171.55/t from the previous week. This price is £2.35/t higher than the price of the 2025 crop (May-26). For comparison, the price of the new crop (Sep-26) in Chicago and Paris is £7.05/t and £3.04/t higher than the price of the old crop (May-26), respectively. The risk of adverse weather conditions for winter 2026 crops is currently higher due to lower temperatures in the Black Sea region.
The small price difference between Paris wheat and maize futures for the 2025 crop suggests that the EU maize balance sheet favours maize prices over wheat prices. In the UK domestic market, the premium for milling wheat remains low.
On 8 January, the USDA released export sales data for the week ending 1 January. Net wheat export sales were recorded at 118.7 Kt, which was lower than the trade had expected. Maize sales were also below trade estimates at 377.6 Kt. However, the current season's wheat and maize exports from the US are higher than last year and the five-year average at this point in time.
One potential future market driver is the USDA's World Agricultural Supply and Demand Estimates (WASDE), due to be published alongside US grain stocks and winter wheat area data. An interesting question is how the pace of US wheat and maize exports could affect ending stocks.
For maize market, the weather situation in Brazil and Argentina is an important factor. According to Brazil government data, maize exports in December 2025 reached 6.13 Mt, compared 4.26 Mt in December 2024.
EU barley exports from 1 July - 4 January reached 5.29 Mt, which is significantly higher than the 2.34 Mt recorded at the same time last season. Also, EU barley imports so far in the current season stand at 0.27 Mt (compared to 0.71 Mt last season), 0.21 Mt of which is from the UK.
Rapeseed
Paris rapeseed futures in £/t (May-26)
May-26 Paris rapeseed futures rose last week and in £/t terms closed both above the 20-day moving average and the psychological threshold of £400/t. The next resistance point and/or target is likely to come from the 50-day moving average, which was above £411/t on Friday.
The 20-day Relative Strength Index (RSI) rose from 19 to 46 (Friday-Friday), reflecting the reversal in market direction.
The lift in £/t terms was a slightly less than the rise in euros (see below) due to sterling strengthening against the euro. This will need to be monitored going forward.
Market drivers
Paris rapeseed futures rose last week due to currency shifts, stronger crude oil prices and optimism over Canadian-Chinese relations. May-26 Paris rapeseed futures rose €20.25/t (4.6%) last week to close at €464.50/t.
Prices for the Feb-26 contract are still higher than those for May-26, at €471.00/t on Friday, partly influenced by technical factors as the contract approaches its last trading day on 30 January.
The euro fell to a four-week low against the US dollar last Friday (ECB) and helped European prices rise, while a weaker Canadian dollar boosted Winnipeg futures.
Geo-politics, including the ongoing uncertainty over the situation in Venezuela, the unrest in Iran and Russian airstrikes in Ukraine, lifted Brent crude oil futures. The nearby contract rose $2.59/barrel (4.3%) last week (Friday-Friday) to $63.34/barrel.
Higher crude oil prices can improve the attractiveness of biodiesel, so this gain also offered support to vegetable oil and oilseed prices.
Expectations that Indonesia will increase its tax on palm oil exports to fund a higher biodiesel blend (B50) later this year, pushed up Malaysian palm oil futures last week (LSEG).
This also offered wider support to vegetable oil prices.